Quick Summary:
Restaurant owners are among the most common targets for merchant cash advance (MCA) funders. Their businesses often generate consistent credit card sales while operating on thin margins and unpredictable cash flow, which are the exact conditions MCA companies look for. If daily MCA payments are cutting into your business’s key expenses — such as payroll, food costs, and rent — know that you don’t need to take on more debt because legal options are available.
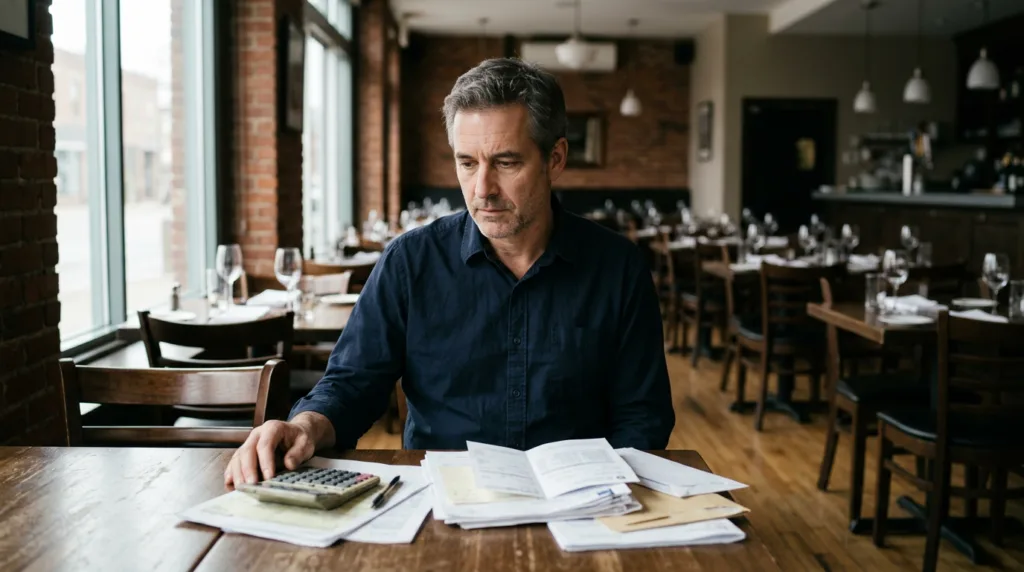
Owning a restaurant isn’t easy. It’s typical for even well-run establishments to operate on razor-thin profit margins while juggling high labor costs, rising food prices, rent, utilities, equipment maintenance, and other fixed expenses. A few slow weeks or an unexpected repair can erase months of profits.
When traditional bank financing isn’t available, MCAs can seem like an easy solution. Approval is usually fast, with minimal underwriting requirements. But for many restaurant owners, that seemingly convenient influx of cash can lead to a cycle of MCA debt that’s difficult to escape.

Why Restaurant Owners End Up Trapped in MCA Debt
Restaurant owners are particularly at risk of falling into the MCA debt trap.
For one, most restaurant sales are processed through credit and debit cards, creating a steady stream of receivables that funders can collect on through daily or weekly holdbacks.
At the same time, restaurants generally operate with net profit margins of just 3% to 5%. That leaves little room for error. Even if sales remain relatively stable, rising costs or unexpected expenses can quickly strain cash flow.
Many restaurant owners also struggle to qualify for traditional business loans, particularly if the business is new or recovering from past financial challenges. MCA brokers frequently market themselves as an alternative, emphasizing funding speed over long-term affordability.
Essentially, what begins as a single advance to cover operational costs often becomes difficult to manage once daily repayments start to cut into cash flow. If revenue drops or expenses increase, owners may find themselves borrowing again simply to keep the business operating.
Warning Signs Your Restaurant Is in Serious MCA Trouble
Not every MCA leads to legal problems. However, certain warning signs may indicate that your business is moving toward a more serious financial situation.
You’re using one advance to pay another
Taking out additional MCAs to cover existing payments — called “MCA stacking” — is one of the clearest signs that debt is becoming unsustainable. Brokers may continue offering new advances as long as your restaurant maintains sufficient card volume, even if additional borrowing makes your financial position worse.
Daily withdrawals are disrupting operations
When automatic debits leave you unable to purchase inventory, schedule enough kitchen staff, or pay vendors on time, the MCA may be interfering with your ability to operate the business successfully.
You may notice:
- Delaying food orders
- Reducing employee hours
- Falling behind with suppliers
- Constantly managing cash from one day to the next
Sales remain steady, but cash keeps disappearing
If your restaurant continues generating revenue but your bank balance never seems to recover, daily MCA withdrawals may be consuming most of your available operating cash.
You’re behind on essential business expenses
Missing payroll, falling behind on rent, or delaying tax payments while continuing to make MCA payments may indicate that your business is prioritizing debt over critical operating expenses.
You’re receiving aggressive collection calls
Some restaurant owners begin receiving persistent calls from collectors, brokers, or companies promising to “consolidate” MCA debt for upfront fees. Before signing any new agreement, it’s important to understand exactly what services are being offered and whether the company has the legal authority to negotiate on your behalf.
Legal and Contract Risks Restaurant Owners Need to Understand
MCA agreements often contain legal provisions that business owners don’t fully understand until problems arise. The following are common clauses in MCA contracts you should be aware of.
- Confession of judgment (COJ): Some MCA agreements include a Confession of Judgment. This provision allows MCA funders to obtain a court judgment without first going through a traditional lawsuit in certain circumstances. A judgment allows the funder to pursue aggressive collection actions, such as levying bank accounts or freezing assets. Although several states have limited or prohibited the use of COJs, they still appear in some agreements and may create significant legal risks.
- UCC lien: Many MCA companies file Uniform Commercial Code (UCC) financing statements against business assets. Depending on the agreement, these liens may affect business equipment, accounts receivable, inventory, and more. A UCC lien can complicate future financing or the eventual sale of the business.
- Personal guarantee: Some restaurant owners are required to personally guarantee their MCA debt. If the business can’t repay it, the funder may attempt to pursue the owner’s personal assets, depending on the terms of the guarantee and local laws.
Not every MCA is legally treated the same
MCAs are structured as purchases of future receivables rather than loans. However, courts evaluate the substance of each agreement. In some cases, an arrangement may be challenged if it functions more like a loan than a true purchase of receivables.
When appropriate, legal defenses may include arguments involving usury laws, contract enforceability, or other issues based on the specific facts and governing state law.
Legal Options for Restaurant Owners With MCA Debt
Restaurant owners facing MCA debt have options other than simply accepting increasingly difficult payment obligations. Here are a few routes you can pursue:
Review your reconciliation rights
Some MCA contracts contain reconciliation clauses that allow payments to be adjusted if the business’s revenue declines. If your agreement includes this provision, you may have the contractual right to request lower payments during slower periods.
However, because these provisions require that you follow specific procedures, it’s important to submit this request in writing before you miss a payment.
Have an attorney review your contracts
An attorney experienced in business debt and MCA litigation should review your agreement to determine whether any part of the contract is unenforceable or subject to legal challenge.
Every case is different, but identifying legal issues early can expand the options available to you.
Consider attorney-led negotiations
It’s possible to negotiate a settlement or restructuring on your own. But this can require a lot of time and energy. Not to mention, you need to have sharp negotiation skills and an understanding of complex MCA rules and the law.
That’s why it’s almost always more effective to have these negotiations handled by legal counsel. Unlike debt relief companies or consultants, attorneys can provide legal advice, evaluate potential claims and defenses, and represent clients in legal disputes with MCA matters.
MCA companies also understand that attorneys can pursue litigation when negotiations fail. That requires a lot of time and money, so funders may be more willing to agree to a settlement rather than get involved in lengthy court battles that competent attorneys can bring to the table.
Act before collection efforts escalate
Timing matters. Once a judgment has been entered, lien sent to your vendors or a bank account has been frozen, resolving the situation often becomes more difficult and more expensive.
Seeking MCA legal advice before signing another advance, before defaulting, or immediately after receiving legal notices can keep more of your options open.
How Tayne Law Group Helps Restaurant Owners Fight MCA Debt
As a restaurant owner struggling with an MCA, taking on more debt isn’t the answer to digging yourself out of the situation. The key to resolving this challenge is securing expert legal guidance.
Tayne Law Group has more than 25 years of experience helping business owners resolve MCA debt, defend lawsuits, vacate confessions of judgment, and challenge UCC liens. Call 866-890-7337 or request a phone consultation. All conversations are confidential, and we never share or sell your information.
Frequently Asked Questions
Why are restaurants such common targets for merchant cash advance funders?
Restaurants process a large volume of card transactions. And because MCA companies can collect payments directly from card revenue or business bank accounts, restaurants are often viewed as attractive borrowers.
Can an MCA company take money directly from my restaurant’s bank account?
It’s standard practice for MCA agreements to authorize automatic withdrawals from a designated business bank account. The specific collection method depends on your contract. If you believe withdrawals are improper or exceed what you originally agreed to, an attorney can review the agreement and advise you of your options.
What happens to my MCA debt if my restaurant closes?
Closing a business does not automatically eliminate your MCA obligations. Depending on the contract, the funder could still pursue remaining business assets, enforce personal guarantees, or seek other legal courses of action. Your rights and obligations depend on the language of the agreement and applicable state law.
Can a personal guarantee on a restaurant MCA put my home or savings at risk?
Potentially. If you signed a personal guarantee, the MCA company may attempt to pursue personal assets if the business can’t cover the debt. The extent of that exposure depends on the guarantee’s terms, applicable law, and any available legal defenses.
What should I look for in legal help with restaurant MCA debt?
Look for a law firm with attorneys who have experience handling MCA disputes, reviewing MCA contracts, negotiating with funders, and representing business owners when litigation becomes necessary. Legal representation offers protections and advocacy that debt settlement companies generally can’t provide.