Quick Summary
A business owner can sue an MCA funder in cases of usury, harmful sales and collection practices, contract breaches, and more. A lawsuit isn’t always the best first course of action, so consult an attorney like Tayne Law Group who can evaluate your agreement to identify potential claims.
MCA deals sometimes include illegal or unethical provisions that could allow you to sue the company. Knowing how to recognize a problematic MCA contract and what to do next can save your business from added financial stress.
Do You Have Grounds to Sue an MCA Company?
In some cases, merchants/debtors may have grounds to sue the MCA providers. These grounds usually come from one or more of the following situations:

- Usury (charging more interest than the law allows)
- Deceptive sales practices
- Improper or excessive bank withdrawals
- Aggressive collection tactics, including harassment or threats
- Breach of contract by the provider
MCA agreements often involve disguised interest rates that function like loans, but are structured to avoid usury laws (i.e., interest rate caps). Funders also often misuse confession of judgment (COJ) clauses that allow a funder to win a judgment without notifying you or going through the normal legal process.
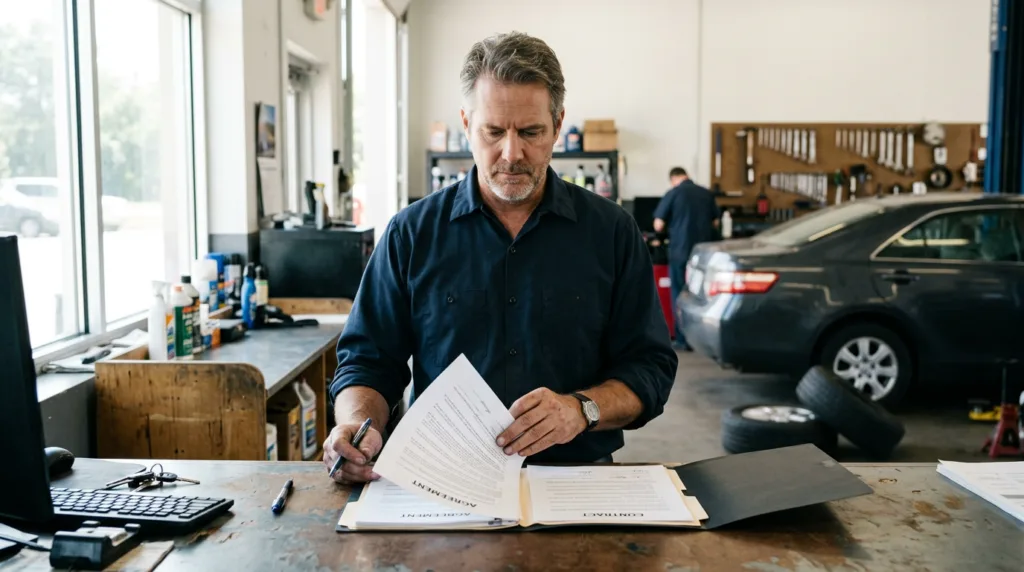
To make sure you have a real case, it’s important to review the contract closely, specifically identifying any one-sided provisions and arbitration or forum-selection clauses that could limit where you can sue. Finally, you’ll have to show that you’ve suffered financial harm from the wrong.
Note: There’s a difference between suing an MCA company and bringing up the same issues as your legal defense if the funder sues you. Both can provide legal relief, but they have different strategies, timelines, and costs. The best approach depends on your situation.
What Legal Claims Can You Bring Against an MCA Company?
Most lawsuits against MCA companies are based on two things: either the agreement is disguised as a usurious loan, or the funder has committed fraud or violated a the law.
- Usury and recharacterization: MCAs and loans are held to different legal standards. If a court deems an MCA contract functions like a loan, it could be subject to usury laws.
- Fraud or nondisclosure: You can sue if the funder misrepresented the terms or costs of the MCA or how the payments would be collected.
- Unconscionability: An MCA agreement that’s found to have extremely one-sided terms could be challenged as unconscionable and unfair.
- Consumer or business protection violations: Many states have laws specifically designed to combat predatory commercial lending practices if it is deemed to be a loan.
- Debt collection or reporting violations: Harassment, threats, or inaccurate credit reporting could be a violation of federal and/or state law.
- Breach of contract and good faith: If the funder violates the MCA contract terms or acts in bad faith, that could be a basis for a lawsuit.
What Can You Recover If You Win an MCA Lawsuit?
The outcome of an MCA lawsuit depends on the nature of the case. The court may order a reduction or full voiding of the remaining balance and, in some cases, may allow you to recover what you’ve already paid. The court may also order the removal of liens, judgments, and negative marks on your credit report tied to the disputed debt. Finally, your business bank accounts may be protected from unauthorized withdrawals going forward.
Depending on the claim, you could also recover statutory damages or have the other party required to pay your legal expenses. These depend heavily on the facts of your case, where you sue and the strength of the case which only an MCA attorney can evaluate your case to determine if this is something to expect.
Should You Sue, or Are There Better Options First?
While a lawsuit can help you recover lost funds or right an injustice, it isn’t always the right first move. Some disputes are better resolved through negotiation or by raising your legal arguments as a legal defense if the funder has already sued you.
Here are some things to consider if you’re wondering whether to sue:
- Cost versus recovery: Litigation takes time and a lot of money. You must weigh if if the amount you could potentially recover versus the cost of suing the company and actually winning and then whether you can recover any money.
- Personal guarantee and countersuit exposure: If you personally guaranteed the advance, suing the funder could result in a countersuit.
- Statute of limitations: Most legal claims have time limits in which you must pursue them, so waiting too long can limit your options.
- Defense versus offense: Some claims are better made as a legal defense if your MCA funder sues you rather than as an offense — and it may be cheaper.
Choosing a different path doesn’t necessarily mean you’re giving in. In many cases, having an attorney negotiate a resolution directly with the funder is a better option than going to court.
Working with an Attorney to Sue an MCA Company
MCA litigation is a specialized area of law. It’s worth working with an attorney who has experience in business debt and commercial finance disputes rather than a general litigator who may be unfamiliar with how these contracts are structured.
Before hiring an attorney, ask about their experience with MCA cases, how they structure their fees, and what timelines you should expect. MCA fees vary from one attorney to the next. Some work on an hourly basis or operate a monthly retainer model. Some also offer specific services, such as an initial contract review or response letter, for flat fees.
If your business has more than one creditor or collection matter, your debt relief attorney can help coordinate your MCA claim alongside your other debts so resolving one issue doesn’t affect another.
If you’re weighing whether to sue an MCA company, the first step is a conversation with an attorney. Tayne Law Group has decades of experience dealing with these types of debts, and we can help. We offer a free phone consultation to review your situation and help you understand your options before you commit to any course of action. Contact us today by calling (866) 890-7337 or filling out our short contact form to schedule a free phone consultation. We never share or sell your information, and all conversations are confidential.
FAQ
What legal grounds do I need to sue an MCA company?
Legal grounds needed to sue an MCA company could include usury violations, abusive or harmful sales or collection tactics, excessive bank withdrawals, or a violation of your original agreement. An attorney can review your situation to see if a lawsuit is warranted.
How can I tell if my MCA agreement is actually a usurious or predatory contract?
Your MCA agreement may be a usurious or predatory contract if it includes effective interest rates far higher than what the state allows, confusing or vague payment terms, or aggressive daily withdrawals that aren’t tied to your business’s revenue.
What evidence should I gather before filing a lawsuit against an MCA company?
Before filing a lawsuit against your MCA company, review your full contract, withdrawal history, and communication between you and the funder. Once your attorney has seen all relevant documentation, they can see if there’s a case.
Can I stop aggressive collections or bank debits while my lawsuit is pending?
In some cases, you may be able to limit further withdrawals or collection activity while the lawsuit is being resolved. Whether this is possible depends on your unique situation, the details of your contract, and the funder’s conduct.
Do I need a specialized attorney to sue an MCA company, and what does it cost?
Yes, MCA litigation is a specialized area of law that requires a true expert. It’s best to work with someone who specializes in MCAs and other forms of business debt resolution. Costs vary by attorney and the complexity of your case, so it’s best to ask about fees during your initial consultation.